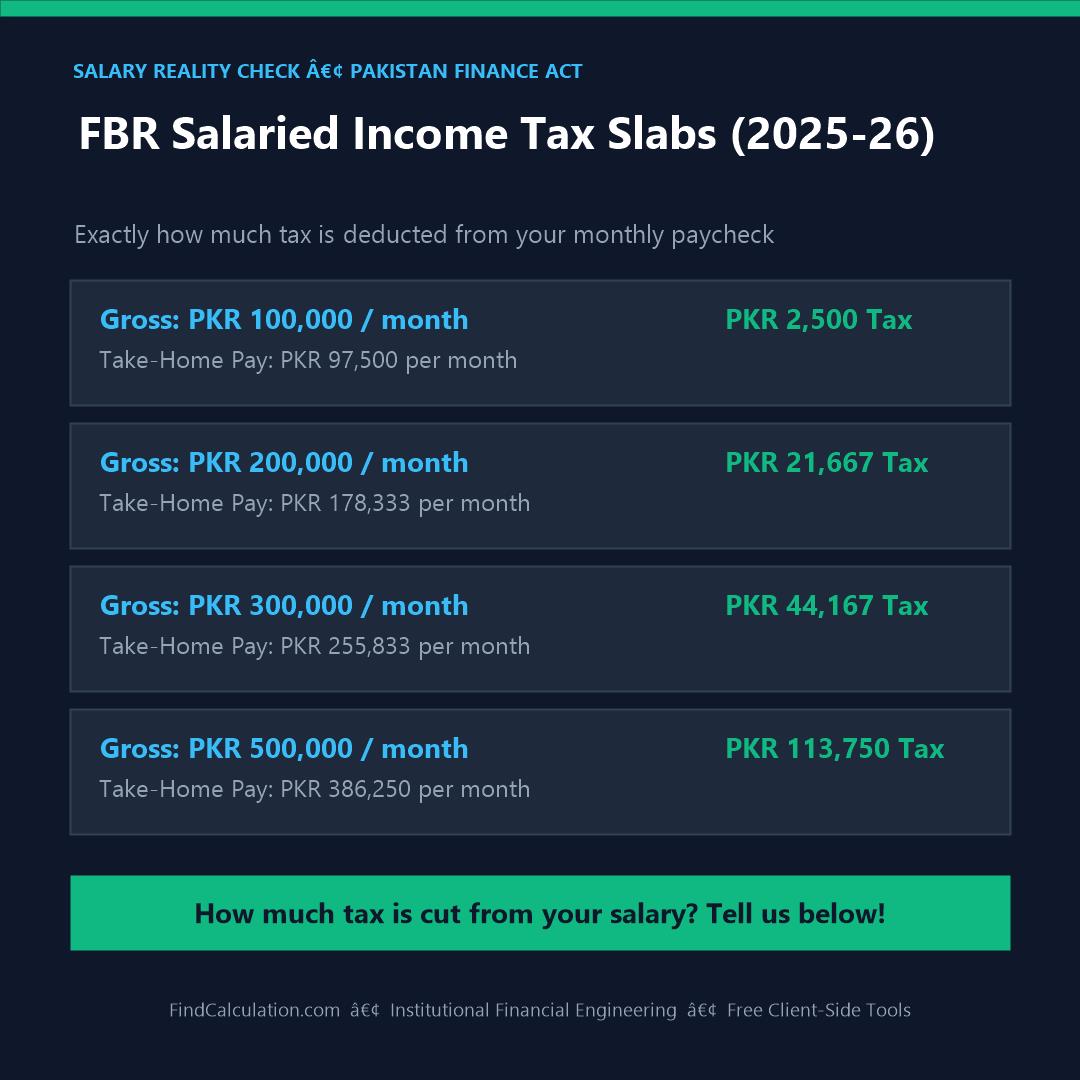
FBR Income Tax Slabs 2025-26: Complete Salary Tax Calculation on 100k to 1M PKR
> Quick Answer: Under the prevailing Federal Board of Revenue (FBR) Finance Act tax code for salaried individuals in Pakistan, annual income up to PKR 600,000 (PKR 50,000/month) is taxed at 0% (Tax Exempt). For incomes above this threshold, progressive marginal tax brackets apply, ranging from 5% on the first taxable slab up to 35% plus super tax surcharges for high earners. For example, an individual earning PKR 150,000/month pays approximately PKR 5,000/month in tax, whereas someone earning PKR 500,000/month incurs PKR 98,333/month in tax, yielding an effective tax rate of 19.67%.
> Executive Summary: This comprehensive tax advisory guide provides an authoritative mathematical breakdown of FBR salaried income tax withholding for Tax Year 2025–2026. We examine taxable income definitions, dissect progressive marginal tax slabs, provide exact worked calculation templates from PKR 100,000 to PKR 1,000,000 monthly, and outline legitimate statutory tax credits (Section 62/63 pensions, mutual funds, education deductions). Test your exact salary tax and take-home pay live on our Pakistan Salary Tax Calculator.
1. Official FBR Salaried Tax Slabs (Finance Act 2025–2026)
Under Section 149 and the First Schedule of the Income Tax Ordinance 2001, an individual is legally classified as "Salaried" if their salary income constitutes more than 75% of their total taxable income:
| Slab No. | Annual Taxable Salary Range (PKR) | Monthly Equivalent Salary (PKR) | Statutory Rate of Income Tax |
|---|---|---|---|
| Slab 1 | Up to PKR 600,000 | Up to PKR 50,000 | 0% (Tax Exempt) |
| Slab 2 | PKR 600,001 to PKR 1,200,000 | PKR 50,001 to PKR 100,000 | 5% of the amount exceeding PKR 600,000 |
| Slab 3 | PKR 1,200,001 to PKR 2,200,000 | PKR 100,001 to PKR 183,333 | PKR 30,000 + 15% of the amount exceeding PKR 1,200,000 |
| Slab 4 | PKR 2,200,001 to PKR 3,200,000 | PKR 183,334 to PKR 266,667 | PKR 180,000 + 25% of the amount exceeding PKR 2,200,000 |
| Slab 5 | PKR 3,200,001 to PKR 4,100,000 | PKR 266,668 to PKR 341,667 | PKR 430,000 + 30% of the amount exceeding PKR 3,200,000 |
| Slab 6 | Above PKR 4,100,000 | Above PKR 341,667 | PKR 700,000 + 35% of the amount exceeding PKR 4,100,000 |
Note on Surcharges: Incomes in the highest brackets are also subject to a 10% surcharge on total tax liability under progressive high-net-worth revenue stabilization clauses.
2. Granular Salary Tax Breakdown Table (PKR 100k to PKR 1M / Month)
Below is the verified tax deductions schedule across all standard executive and professional salary levels:
| Monthly Gross Salary (PKR) | Annual Gross Salary (PKR) | Applicable Slab | Annual Tax Liability (PKR) | Monthly Tax Withholding (PKR) | Net Monthly Take-Home (PKR) | Effective Tax Rate (%) |
|---|---|---|---|---|---|---|
| PKR 100,000 | PKR 1,200,000 | Slab 2 | PKR 30,000 | PKR 2,500 | PKR 97,500 | 2.50% |
| PKR 150,000 | PKR 1,800,000 | Slab 3 | PKR 120,000 | PKR 10,000 | PKR 140,000 | 6.67% |
| PKR 200,000 | PKR 2,400,000 | Slab 4 | PKR 230,000 | PKR 19,167 | PKR 180,833 | 9.58% |
| PKR 250,000 | PKR 3,000,000 | Slab 4 | PKR 380,000 | PKR 31,667 | PKR 218,333 | 12.67% |
| PKR 300,000 | PKR 3,600,000 | Slab 5 | PKR 550,000 | PKR 45,833 | PKR 254,167 | 15.28% |
| PKR 400,000 | PKR 4,800,000 | Slab 6 | PKR 945,000 | PKR 78,750 | PKR 321,250 | 19.69% |
| PKR 500,000 | PKR 6,000,000 | Slab 6 | PKR 1,365,000 | PKR 113,750 | PKR 386,250 | 22.75% |
| PKR 750,000 | PKR 9,000,000 | Slab 6 + Surch. | PKR 2,415,000 | PKR 201,250 | PKR 548,750 | 26.83% |
| PKR 1,000,000 | PKR 12,000,000 | Slab 6 + Surch. | PKR 3,465,000 | PKR 288,750 | PKR 711,250 | 28.88% |
3. Step-by-Step Worked Mathematical Example: PKR 250,000/Month
Let us examine the exact mathematical formula for a gross monthly salary of PKR 250,000:
This places the taxpayer into Slab 4 (PKR 2,200,001 to PKR 3,200,000):
4. Legitimate Statutory Tax Deductions & Credits (Section 62 / 63)
Salaried employees in Pakistan can legally reduce their tax burden by taking advantage of statutory allowances:
1. Voluntary Pension System (VPS) Contributions (Section 63)
Investments in registered Islamic or conventional voluntary pension funds (e.g., Meezan Tahaffuz Pension Fund, Al-Ameen Islamic Retirement Savings) qualify for a tax credit up to 20% of annual taxable income. For an executive earning PKR 3M annually, contributing PKR 600k into VPS can yield direct tax savings of up to PKR 150,000!
2. Full-Time Teacher / Researcher Allowance
Full-time teachers and researchers at non-profit universities or government educational institutions are entitled to a 25% reduction in total income tax liability.
3. Medical Allowance vs Medical Reimbursement
Under Clause 139 of the Second Schedule:
- Medical allowance is tax-exempt up to 10% of basic salary (provided medical reimbursement is not availed).
- Actual hospitalization expenses reimbursed by employer are 100% tax-free if provided under corporate policy.
5. Frequently Asked Questions (FAQ)
Q1: Is the tax on salary calculated on basic pay or gross pay?
A: In Pakistan, tax is assessed on Total Gross Taxable Income, which includes basic pay, cost of living allowances, bonus, and special utility allowances. Only specific statutory exemptions (like 10% medical allowance) are deductible.
Q2: What happens if an employee fails to file their annual income tax return?
A: Non-filers are placed on the Inactive Taxpayer List (ITL), subjecting them to 100% higher withholding tax rates on cash withdrawals, banking transactions, car purchases, and property registrations.
Q3: When does the Pakistani tax year begin and end?
A: The fiscal Tax Year begins on July 1st and concludes on June 30th of the subsequent calendar year.
6. Interactive Calculator Walkthrough
To verify your exact salary slip numbers:
- 1
- 2Input your monthly gross income or basic plus allowances.
- 3Toggle any tax credits or pension contributions.
- 4Instantly view your monthly withholding tax, annual tax obligation, and net bank take-home salary.
Tax Advisory Notice: This publication reflects official Federal Board of Revenue (FBR) Finance Act legislation for Tax Year 2025–2026. Consult licensed Chartered Accountants (CPA/FCA) or tax lawyers for corporate filings.