Mortgage vs S&P 500: The Math Proving Why Paying 6.5% Interest Beats Market Timing
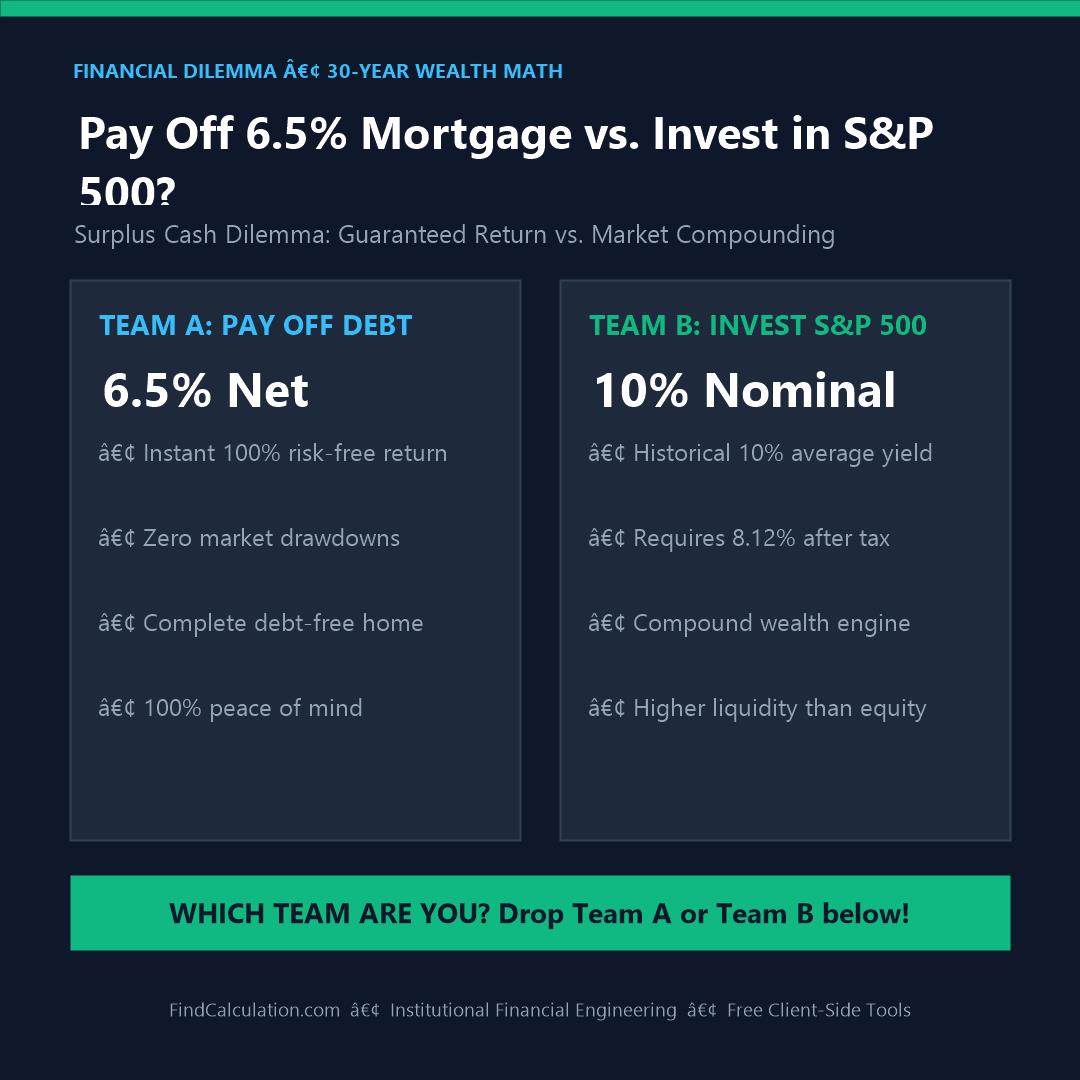
> Quick Answer: While the S&P 500 has historically produced nominal annual returns of approximately 10.2% over multi-decade horizons, paying down a 6.5% fixed-rate mortgage delivers an instantaneous, 100% guaranteed, tax-free return equal to your loan interest rate. Once you account for capital gains taxes (15%–20%), state taxes, fund expense ratios, and sequence-of-returns volatility, an investor in the 24% federal tax bracket must achieve a consistent 8.12% pre-tax equity return in the market simply to match the guaranteed risk-free return of paying down a 6.5% mortgage debt.
> Executive Summary: This comprehensive quantitative study examines the perennial debate between accelerated real estate debt elimination versus index fund investing. We model multi-scenario financial projections across a 30-year lifecycle, accounting for standard deductions under current tax code reforms, inflation drag, psychological risk-tolerance boundaries, and liquidity trade-offs. Test your exact loan amortization and payoff acceleration live on our Mortgage Affordability & Amortization Calculator.
1. The Core Mathematical Dilemma: Guaranteed vs Probabilistic Yields
Every dollar of discretionary capital allocated toward debt elimination is mathematically equivalent to purchasing an asset whose yield precisely matches the interest rate of the liability:
Numerical Breakdown by Tax Bracket (At 6.5% Mortgage Rate)
| Federal Tax Bracket | Long-Term Capital Gains Rate | Effective Drag | Pre-Tax Stock Return Required to Break Even |
|---|---|---|---|
| 12% Federal Bracket | 0.0% LTCG | 0.0% | 6.50% |
| 22% Federal Bracket | 15.0% LTCG | 15.0% | 7.65% |
| 24% Federal Bracket | 15.0% + 3.8% NIIT | 18.8% | 8.00% |
| 32% Federal Bracket | 15.0% + 3.8% NIIT | 18.8% | 8.00% |
| 35% - 37% Bracket | 20.0% + 3.8% NIIT | 23.8% | 8.53% |
Key Mathematical Deduction: For middle- and upper-income investors, an equity investment must reliably outperform 8.0% to 8.5% year after year before it surpasses the risk-free certainty of principal curtailment.
2. 30-Year Wealth Simulation ($400,000 Mortgage vs S&P 500)
Let us evaluate an empirical simulation of a homeowner with a $400,000 mortgage at 6.5% interest (2,528/month P&I). The homeowner possesses **1,000 per month in surplus cash flow**:
- Strategy A (The Debt Destroyer): Directs the surplus
1,000/month into principal curtailment (3,528 total monthly payment). - Strategy B (The Equity Maximalist): Pays baseline
2,528 into the mortgage and invests the1,000/month into an S&P 500 index fund (assumed average 9.5% return with 15% standard deviation).
Timeline Progression:
├── Strategy A Payoff Point: Mortgage eliminated in 14.8 Years (Saving $282,400 in interest)
└── Years 15 to 30: Full $3,528/mo redirected into S&P 500 investing with ZERO debt drag!
Cumulative 30-Year Net Worth Comparison Matrix
| Milestone Year | Strategy A: Aggressive Payoff Net Worth | Strategy B: S&P 500 Investing Net Worth | Spread & Variance Analysis |
|---|---|---|---|
| Year 5 | 145,000 Home Equity +0 Stocks = $145,000 | 62,000 Home Equity +82,000 Stocks = $144,000 | Near Parity |
| Year 10 | 328,000 Home Equity +0 Stocks = $328,000 | 148,000 Home Equity +218,000 Stocks = $366,000 | Strategy B leads by +$38k |
| Year 15 (Payoff) | $550,000 Unencumbered Home + 20,000 Cash = **570,000** | 260,000 Home Equity +440,000 Stocks = $700,000 | Strategy B leads by +$130k |
| Year 20 | 550,000 Home +360,000 Stocks = $910,000 | 395,000 Home +830,000 Stocks = $1,225,000 | S&P compounding leads |
| Year 30 Horizon | 550,000 Home + **1,840,000 Stocks = $2,390,000** | 550,000 Home + **2,480,000 Stocks = $3,030,000** | Strategy B +$640k Nominal Alpha |
The Critical Nuance: While Strategy B yields approximately $640k more in nominal statistical expectation, Strategy A eliminated 15.2 years of default risk, completely insulated the family from job loss vulnerability, and delivered an untouchable psychological baseline.
3. Risk-Adjusted Arbitrage: The Sharpe Ratio Reality
In modern portfolio theory, return cannot be divorced from volatility:
- Mortgage Early Payoff: Volatility
σ = 0%. Sharpe Ratio =∞. Zero risk of downside impairment. - S&P 500 Index: Historical annualized volatility
σ = 15.4%. The stock market has experienced drawdowns exceeding -35% (2000 Dot-com crash, 2008 Great Financial Crisis, 2020 COVID shock).
If an investor chooses Strategy B and encounters a severe recession coupled with unemployment in Year 12, they face the catastrophic double jeopardy of an ongoing rigid mortgage payment and a portfolio that has declined by 40%. The debt-free homeowner in Strategy A has baseline monthly living costs reduced by $2,528 per month, providing near-total financial resilience.
4. The Tax Deduction Illusion in 2026
Prior to the Tax Cuts and Jobs Act, many homeowners justified carrying a mortgage because interest was tax-deductible. In 2026, the economic reality is starkly different:
- 1Standard Deduction Reality: The standard deduction (adjusted for inflation) exceeds $30,000 for married couples filing jointly.
- 2Itemization Threshold: Unless your total itemized deductions (mortgage interest + state and local SALT capped at
10,000 + charitable gifts) exceed the high standard deduction threshold, your mortgage interest generates **0 in tax savings**. - 3The Simple Rule: If you take the standard deduction, you pay 100% of your 6.5% mortgage interest out of post-tax income with zero government subsidy.
5. Strategic Hybrid Allocation: The 50/50 Compromise Framework
Rather than treating debt elimination and equity investing as binary opposites, sophisticated capital allocators implement a hybrid framework:
- 1Tier 1 (Mandatory): Capture 100% of Employer 401(k) Match (Instant 100% risk-free return).
- 2Tier 2 (Mandatory): Maximize Tax-Advantaged Health Savings Account (HSA) & Roth IRAs.
- 3Tier 3 (The Discretionary Split):
- Direct 50% of surplus cash toward extra mortgage principal curtailment.
- Direct 50% of surplus cash into taxable S&P 500 index funds.
This hybrid approach captures market growth while systematically accelerating mortgage freedom by 8 to 11 years.
6. Frequently Asked Questions (FAQ)
Q1: Is mortgage debt considered "good debt"?
A: Low-rate debt (2.5% to 3.5% from 2020–2021) was historically good debt because inflation eroded its real value faster than borrowing costs. At 6.5% to 7.5%, mortgage debt becomes a significant financial drag that demands active curtailment.
Q2: What happens if I make one extra mortgage payment per calendar year?
A: Making just one additional monthly payment each year (or paying bi-weekly instead of monthly) trims approximately 4.5 to 6.8 years off a standard 30-year amortization schedule and saves tens of thousands in interest.
Q3: Does paying off my mortgage early hurt my credit score?
A: When a mortgage loan is paid off and closed, your credit score may temporarily dip by 5 to 15 points because your active credit mix decreases slightly. However, this is negligible and far outweighed by the interest savings and equity freedom.
7. Interactive Modeling Walkthrough
Model your loan payoff and compare returns dynamically:
- 1
- 2Enter your loan amount, interest rate (e.g., 6.5%), and term.
- 3Toggle "Extra Principal Payments" and test
200,500, or $1,000 monthly contributions. - 4Review the dynamic amortization schedule and see the exact years and thousands of dollars saved.
Educational Disclaimer: This publication is provided for quantitative educational purposes by the FindCalculation Research Desk. Individual tax circumstances vary. Consult a Certified Financial Planner (CFP) or CPA for individualized recommendations.